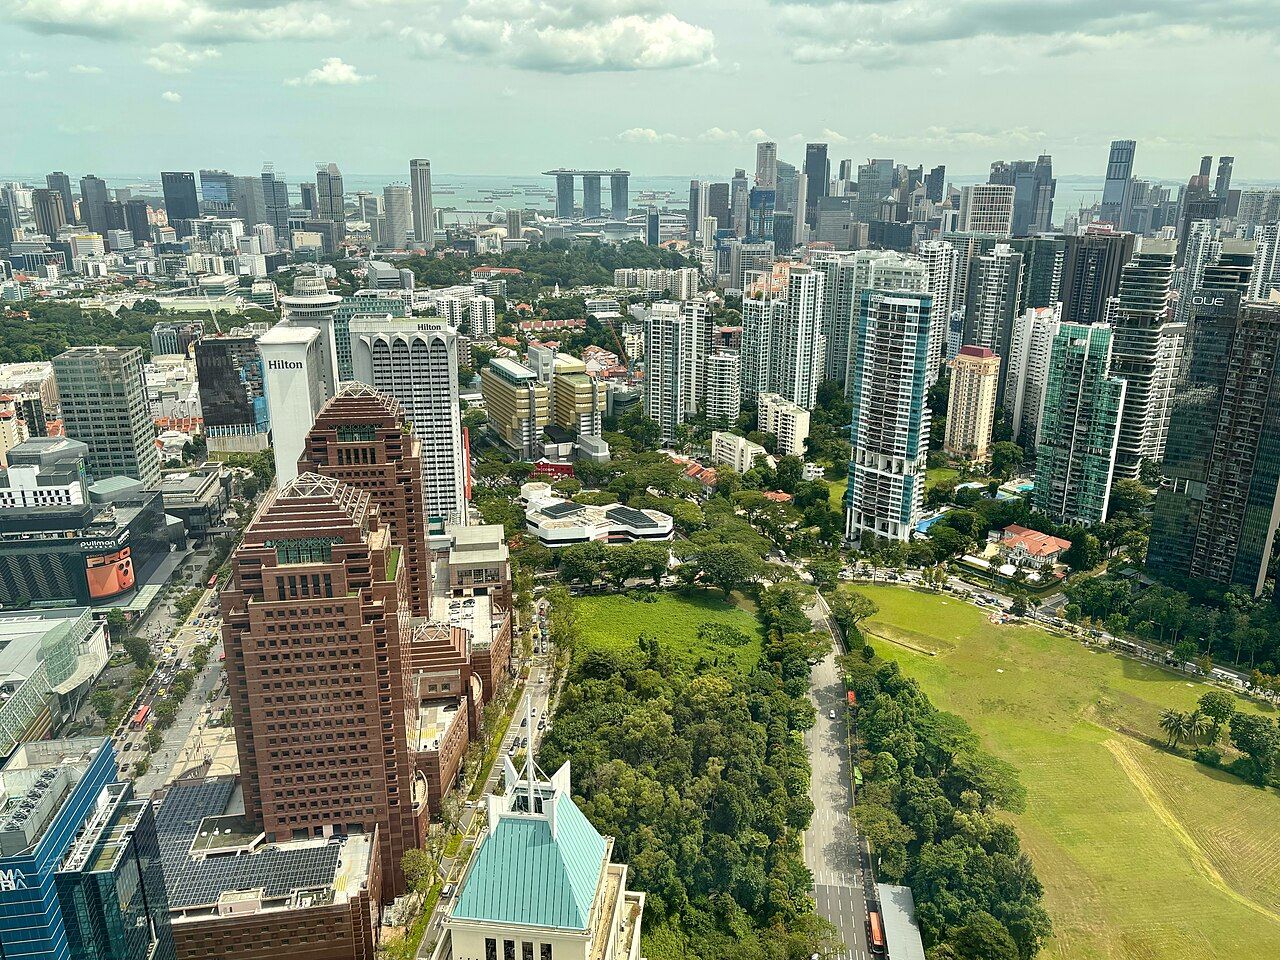
Singapore's private home market cooled in the second quarter of 2026, but prime-district condos went the other way. According to the Urban Redevelopment Authority's (URA) final 2Q2026 statistics released on 24 July 2026, non-landed homes in the Core Central Region (CCR) – the district band that covers Orchard, Tanglin, Bukit Timah, Newton and Novena – rose 1.8% in the quarter. Condo prices in the Rest of Central Region (RCR) fell 1.2%, and those in the suburbs (OCR) slipped 0.1%.
For buyers watching Districts 9, 10 and 11, it was the CCR's strongest quarter of 2026 so far – up from a 0.6% rise in Q1. Here is what the numbers show, why analysts think prime homes held up, and what it could mean if you're looking at a freehold or large-format home in the city.
Q2 2026 at a glance
URA's overall private residential price index rose 0.5% in Q2 2026, slower than the 0.9% gain in Q1. That brought the first-half increase to 1.4%, below the 1.8% recorded in the first half of 2025. The headline figure, however, hides very different moves underneath:
| URA price index (quarter-on-quarter) | Q1 2026 | Q2 2026 |
|---|---|---|
| Overall private residential | +0.9% | +0.5% |
| Landed homes | −0.4% | +2.5% |
| Non-landed (all regions) | +1.3% | −0.1% |
| Non-landed – Core Central Region (CCR) | +0.6% | +1.8% |
| Non-landed – Rest of Central Region (RCR) | +0.8% | −1.2% |
| Non-landed – Outside Central Region (OCR) | +2.2% | −0.1% |
The CCR was the only non-landed segment to rise, and it accelerated from Q1. URA's flash estimate on 1 July had put the CCR gain at 2.0%; the final figure was revised slightly down to 1.8%, which still left prime condos well ahead of the rest of the market.
Prime rents are rising too
Prices were not the only bright spot. Rents for non-landed homes in the CCR rose 1.2% in Q2, up from 0.5% in Q1. RCR rents were unchanged and OCR rents dipped 0.3%. Overall private rents rose 0.7%.
Speaking to The Business Times, Wong Xian Yang of Cushman & Wakefield said sustained wealth migration into Singapore is expected to support leasing demand in the CCR, while CBRE's Tricia Song pointed to limited upcoming supply in the CCR as a factor likely to support rents there.
One number worth watching: the vacancy rate for completed private homes in the CCR edged up to 8.3% at end-Q2, from 8.2% in Q1, and it remains higher than in the RCR (6.1%) and OCR (5.6%). Rising rents alongside a higher vacancy rate suggest demand is concentrated in the better-located, newer prime projects rather than spread evenly across the region.
Why prime condos outperformed
Analysts quoted by EdgeProp after the flash estimate gave three main reasons:
- A bigger pool of local buyers with the means to buy prime homes. Demand for higher-end condos came from a growing pool of Singapore citizens and permanent residents, some of whom have moved from renting to owning.
- A narrowing price gap. Buyers are seeing value in prime projects as the gap between CCR prices and those in the RCR and OCR has narrowed. When a city-fringe new launch costs almost as much as a prime-district one, the prime address becomes easier to justify.
- Well-received prime launches. New projects such as River Modern and The Robertson Opus in District 9 were cited as contributing to the CCR gains.
Supply: plenty island-wide, less in the prime districts
The Government is keeping land supply high. URA said 4,745 private units will be launched under the Confirmed List of the Government Land Sales (GLS) programme for the second half of 2026, bringing the full-year Confirmed List supply to 9,320 units – more than 50% above the average of the past 10 years. About 60,600 private homes (including ECs) are expected to be completed over the next few years.
Developer activity itself was steady rather than hectic. Developers launched 1,783 private units (excluding ECs) in Q2 and sold 2,141, both similar to Q1. According to The Business Times, the bulk of upcoming completions are in the RCR and OCR – one reason analysts such as CBRE expect prime rents to hold up.
What the analysts expect for the rest of 2026
Forecasts reported by EdgeProp when the flash estimate came out were for moderate, not runaway, growth:
- Huttons estimated about a dozen private launches with roughly 3,567 units in 2H2026, and kept its full-year price growth forecast at 2–5%.
- CBRE expects 7,500 to 8,500 new private homes to be sold in 2026, with prices growing 2–4%.
- ERA projects 9,000 to 10,000 new home sales this year.
- Knight Frank's Leonard Tay suggested keeping an eye on land awarded under the GLS programme as a precursor to possible price increases in the rest of 2026 and early 2027.
URA itself struck a cautious note, saying the macroeconomic outlook remains highly uncertain and advising households to be prudent when buying property and taking on mortgages. Its flash estimate for Q3 2026 is due in early October.
What this means if you're looking at D9, D10 or D11
Q2 2026 is one quarter, not a trend, and past performance is no guarantee of what comes next. But three points stand out for prime-district buyers:
- The price gap is doing some of the selling. If you are comparing a city-fringe launch with a prime-district one, compare the price per square foot side by side. The difference may be smaller than you expect.
- Owner-occupiers are driving demand. The analysts' explanation – locals upgrading and renters becoming owners – points to buyers who plan to live in the home. For those buyers, location, school proximity and unit size matter more than short-term price moves.
- Freehold in the prime districts is scarce. GLS sites are sold on 99-year leases, and much of the upcoming supply is outside the CCR. Freehold boutique projects in District 11 – like 32 Gilstead, whose 14 units are fully sold – tend to be small and few.
If you are looking for a similar prime-district home, current launches include Dunearn House, Chancery Hill Collection and The Serra Residences in District 11, UpperHouse at Orchard and 21 Anderson in District 10, and River Modern and The Robertson Opus in District 9. WhatsApp us for price lists, floor plans and showflat appointments.
This article is for general information only and is not financial or investment advice. Figures are from the sources below as at their publication dates.
Sources
- URA, Release of 2nd Quarter 2026 real estate statistics, 24 July 2026
- URA, Release of flash estimate for 2nd Quarter 2026 private residential property price index, 1 July 2026
- The Business Times, Private residential rents rise 0.7% in Q2 as home prices inch up 0.5%: URA, 24 July 2026
- EdgeProp, Non-landed private home prices fell by 0.1% in second quarter, with 1.4% drop in RCR: flash estimates